An insurance repaint is paid on scope, not on preference. The insurer covers returning the damaged surfaces to the condition they were in immediately before the loss, which usually means the affected wall or ceiling coated corner to corner, not the whole house repainted while the trades are on site.
Everything past that scope is yours to fund: a colour change, a better finish than you had, the rooms that were never touched. Knowing this at the start saves the argument that otherwise turns up with the final invoice.
Who decides what actually gets painted?
An assessor or loss adjuster inspects the damage and writes a scope of works. That document, not your painter’s quote, is what the claim settles against. Painters price it line by line, and any variation has to be approved before the work happens rather than explained afterwards.
If the scope looks wrong to you or to your painter, say so before anything starts. The common case is water that travelled further than the assessor saw: down a wall cavity, along a top plate, out into the next room. Photographs and moisture readings taken at the time are what get a scope extended. A phone call three weeks later, once the lining has already been replaced, generally does not.

Why will they not repaint the whole room?
Because the policy restores what was lost, and the undamaged half of the room was not lost. In practice most insurers accept coating a full surface corner to corner rather than patching, because a spot repair on a wall that has been up for a decade never matches. The existing paint has faded, yellowed and collected dirt, and a fresh tin of the identical colour code reads as a different colour under raking light.
Where you have to make the case is the ceiling that runs through into a hallway, or the wall that carries past an open-plan corner with no natural break to stop at. The argument that works is technical rather than emotional: there is no break line to finish against, so a partial repaint leaves a visible edge, and the surface has to be coated in full to return it to its pre-loss appearance.
What is betterment, and when do you pay it?
Betterment is any part of the work that leaves you better off than you were before the damage. Insurers do not pay for it, and they are not being awkward about it. It is simply how the policy is written.
| Work | Who normally pays |
|---|---|
| Replacing water-damaged lining and re-stopping the joints | Claim |
| Sealing a stain so it cannot bleed back through the new paint | Claim |
| Coating the damaged ceiling corner to corner in the same colour | Claim |
| Access equipment needed to reach the damaged surface | Claim |
| Your policy excess | You |
| Changing the colour while the painter is already on site | You |
| Lifting trim from a basic builder’s finish to a full enamel system | You, as betterment |
| Repainting undamaged rooms elsewhere in the house | You |
| Repainting sound exterior elevations so they match the repaired one | Negotiated, often shared |
The clean way to handle that split is one quote with two subtotals: the scope work priced against the assessor’s line items, and your own extras priced separately underneath. Then nobody is confused about which portion the insurer is settling and which portion you are paying directly.

Do I claim with my insurer or the Natural Hazards Commission?
Start with your private insurer either way. Building cover through NHCover applies to earthquake, natural landslip, volcanic activity, hydrothermal activity and tsunami, and almost every New Zealand insurer lodges and manages that claim on the Commission’s behalf. You make one call, not two.
Storm and flood work differently, and it catches people out. For those two, NHCover is land cover only, so storm or flood damage to the house itself — and the repaint that follows it — sits with your private insurer rather than the Commission.
Two details are worth carrying around. The NHCover residential building cap rose from $150,000 plus GST to $300,000 plus GST on 1 October 2022, taking effect from each policy’s first anniversary date after that, and your private policy responds above the cap. And while you have a maximum of two years to lodge a claim after a natural hazard event, the Commission encourages you to claim within three months, and says a longer delay may affect its ability to assess the claim and could see it declined.
Which leads to the useful habit after any sudden event: get the damage recorded before anyone makes it disappear. Emergency work to stop further damage is expected and will not count against you, but permanent repairs carried out before the loss has been documented are very hard to price into a claim afterwards.
Who chooses the painter?
It depends on how the claim is settled. On a managed repair the insurer appoints a project manager or builder who brings their own subcontractors, and your input is mostly limited to colour and access. On a cash settlement you engage your own trades and the money is paid to you.
Plenty of insurers will also accept your preferred contractor on a managed repair if the pricing is reasonable and the trade is qualified. Asking costs nothing, and it is worth asking before you sign anything, because swapping contractors mid-claim is far harder than nominating one at the start.
What should the quote itemise?
- The scope item numbers each price relates to, so the assessor can match them up quickly
- Make-good and preparation shown separately from the painting itself
- Number of coats and the product used on each surface
- Access equipment as its own line rather than buried in a rate
- Insurer-funded scope and owner-funded extras as separate subtotals
- Exclusions in writing: moving contents, taking down curtains and fittings, electrical work

What slows an insurance repaint down?
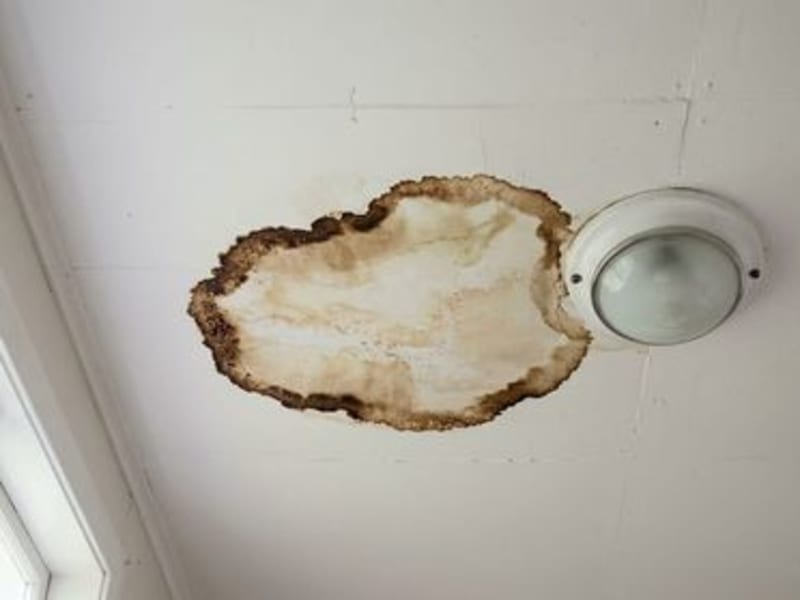
Drying, almost always. Water-damaged framing and lining have to be dried and proven dry with meter readings before new lining goes on, and fresh stopping has to dry properly before it is sealed. Paint over a wall that is still carrying moisture and the stain returns through the new coating, which turns one job into two.
A Wellington winter makes this harder rather than easier. High humidity and short drying windows mean a wall that would be ready in a few days in February can take considerably longer in July, and no amount of pressure changes that. Where the repair involves new lining and stopping, budget the time instead of fighting it.
When is it not worth claiming at all?
If the repair sits close to or under your excess, paying for it directly is usually the better deal. A small claim still goes on your history, and the effect on your next renewal can outlast the saving. A stained ceiling from a one-off overflow, where the cause has already been fixed, is often cheaper to simply repair and repaint as ordinary interior work.
Claim the ones that matter. Handle the small stuff yourself and keep your record clean.
If you have a scope of works and want it priced, or you want someone to look at damage and tell you honestly whether it is a claim or a Saturday, get in touch.
Related Articles

Need Help With Your Painting Project?
Wellington Decorators has been transforming homes across the Wellington region since 2023, led by a founder with 18+ years in the trade. As Registered Master Painters, we back every job with a 5-year workmanship guarantee.
Prefer to talk? Call us now 027 458 6465